Application 4: Ramsey policy against the Taylor rule
Question. From the 2022Q2 peak, what would optimal policy under commitment do instead of the Taylor rule, under rational expectations (RE) and with learners, for four sets of loss weights?
The loss
Every run of a model package with a policy section reports a discounted loss with the
weights of policy.loss:
where for the Smets and Wouters (2007) model (SW07) \(\hat\pi = 4\pi\) and \(\hat r = 4r\) are
annualized deviations from the steady state, \(x = y - y^f\) is the output gap and
\(\delta = \bar\beta\gamma\) is the discount of the SW07 Phillips curve. The targets come from
spec.policy.targets in models/sw07/model_spec.m:
spec.policy = struct( ...
    'instrument', 'r', ...
    'rule_label', 'Monetary policy rule, Taylor rule on the output gap y-yf', ...
    'targets', struct('pinf', '4*pinf', 'ygap', 'y - yf', 'r', '4*r', 'dr', '4*(r - r{-1})'), ...
    'discount', '$cbetabar$*$cgamma$');
Scenario files
scenarios/sw07/app4_ramsey/ has 14 files. The rule runs report the loss over 80 quarters
(the forecast continued with zero shocks):
function cfg = a4_rule_re()
cfg = a1_re();
cfg.id = 'a4_rule_re';
cfg.policy.loss_horizon = 80;
cfg.expectations.re_info = 'current';   % Ramsey policy needs period-t RE information
end
Every app-4 file sets period-t RE information, the project's only deviation from its baseline. The Ramsey runs switch the rule off and set the weights:
function cfg = a4_ramsey_balanced_re()
cfg = a4_rule_re();
cfg.id = 'a4_ramsey_balanced_re';
cfg.policy.mode = 'ramsey';
cfg.policy.type = 'commitment';
cfg.policy.loss = struct('pinf', 1, 'ygap', 0.5, 'r', 0.1, 'dr', 0);
cfg.compare_with = {'a4_rule_re'};
end
| Weight set | policy.loss |
|---|---|
| balanced | struct('pinf', 1, 'ygap', 0.5, 'r', 0.1, 'dr', 0) |
| hawk | struct('pinf', 1, 'ygap', 0.1, 'r', 0.1, 'dr', 0) |
| dove | struct('pinf', 1, 'ygap', 1, 'r', 0.1, 'dr', 0) |
| smooth | struct('pinf', 1, 'ygap', 0.5, 'r', 0.1, 'dr', 0.5) |
Each weight set has three files: _re (anchored RE agents), _re_mc (model-consistent RE
agents, cfg.expectations.re_variant = 'model_consistent': the RE Ramsey benchmark) and
_learn (copies the policy block of the _re file into a4_rule_learn).
The RE benchmark
Anchored RE agents keep the Taylor-rule forecast under a Ramsey plan, so the _re_mc runs
are the RE benchmark and the learning Ramsey loss is not a clean gain from optimal policy
(Monetary policy).
Results
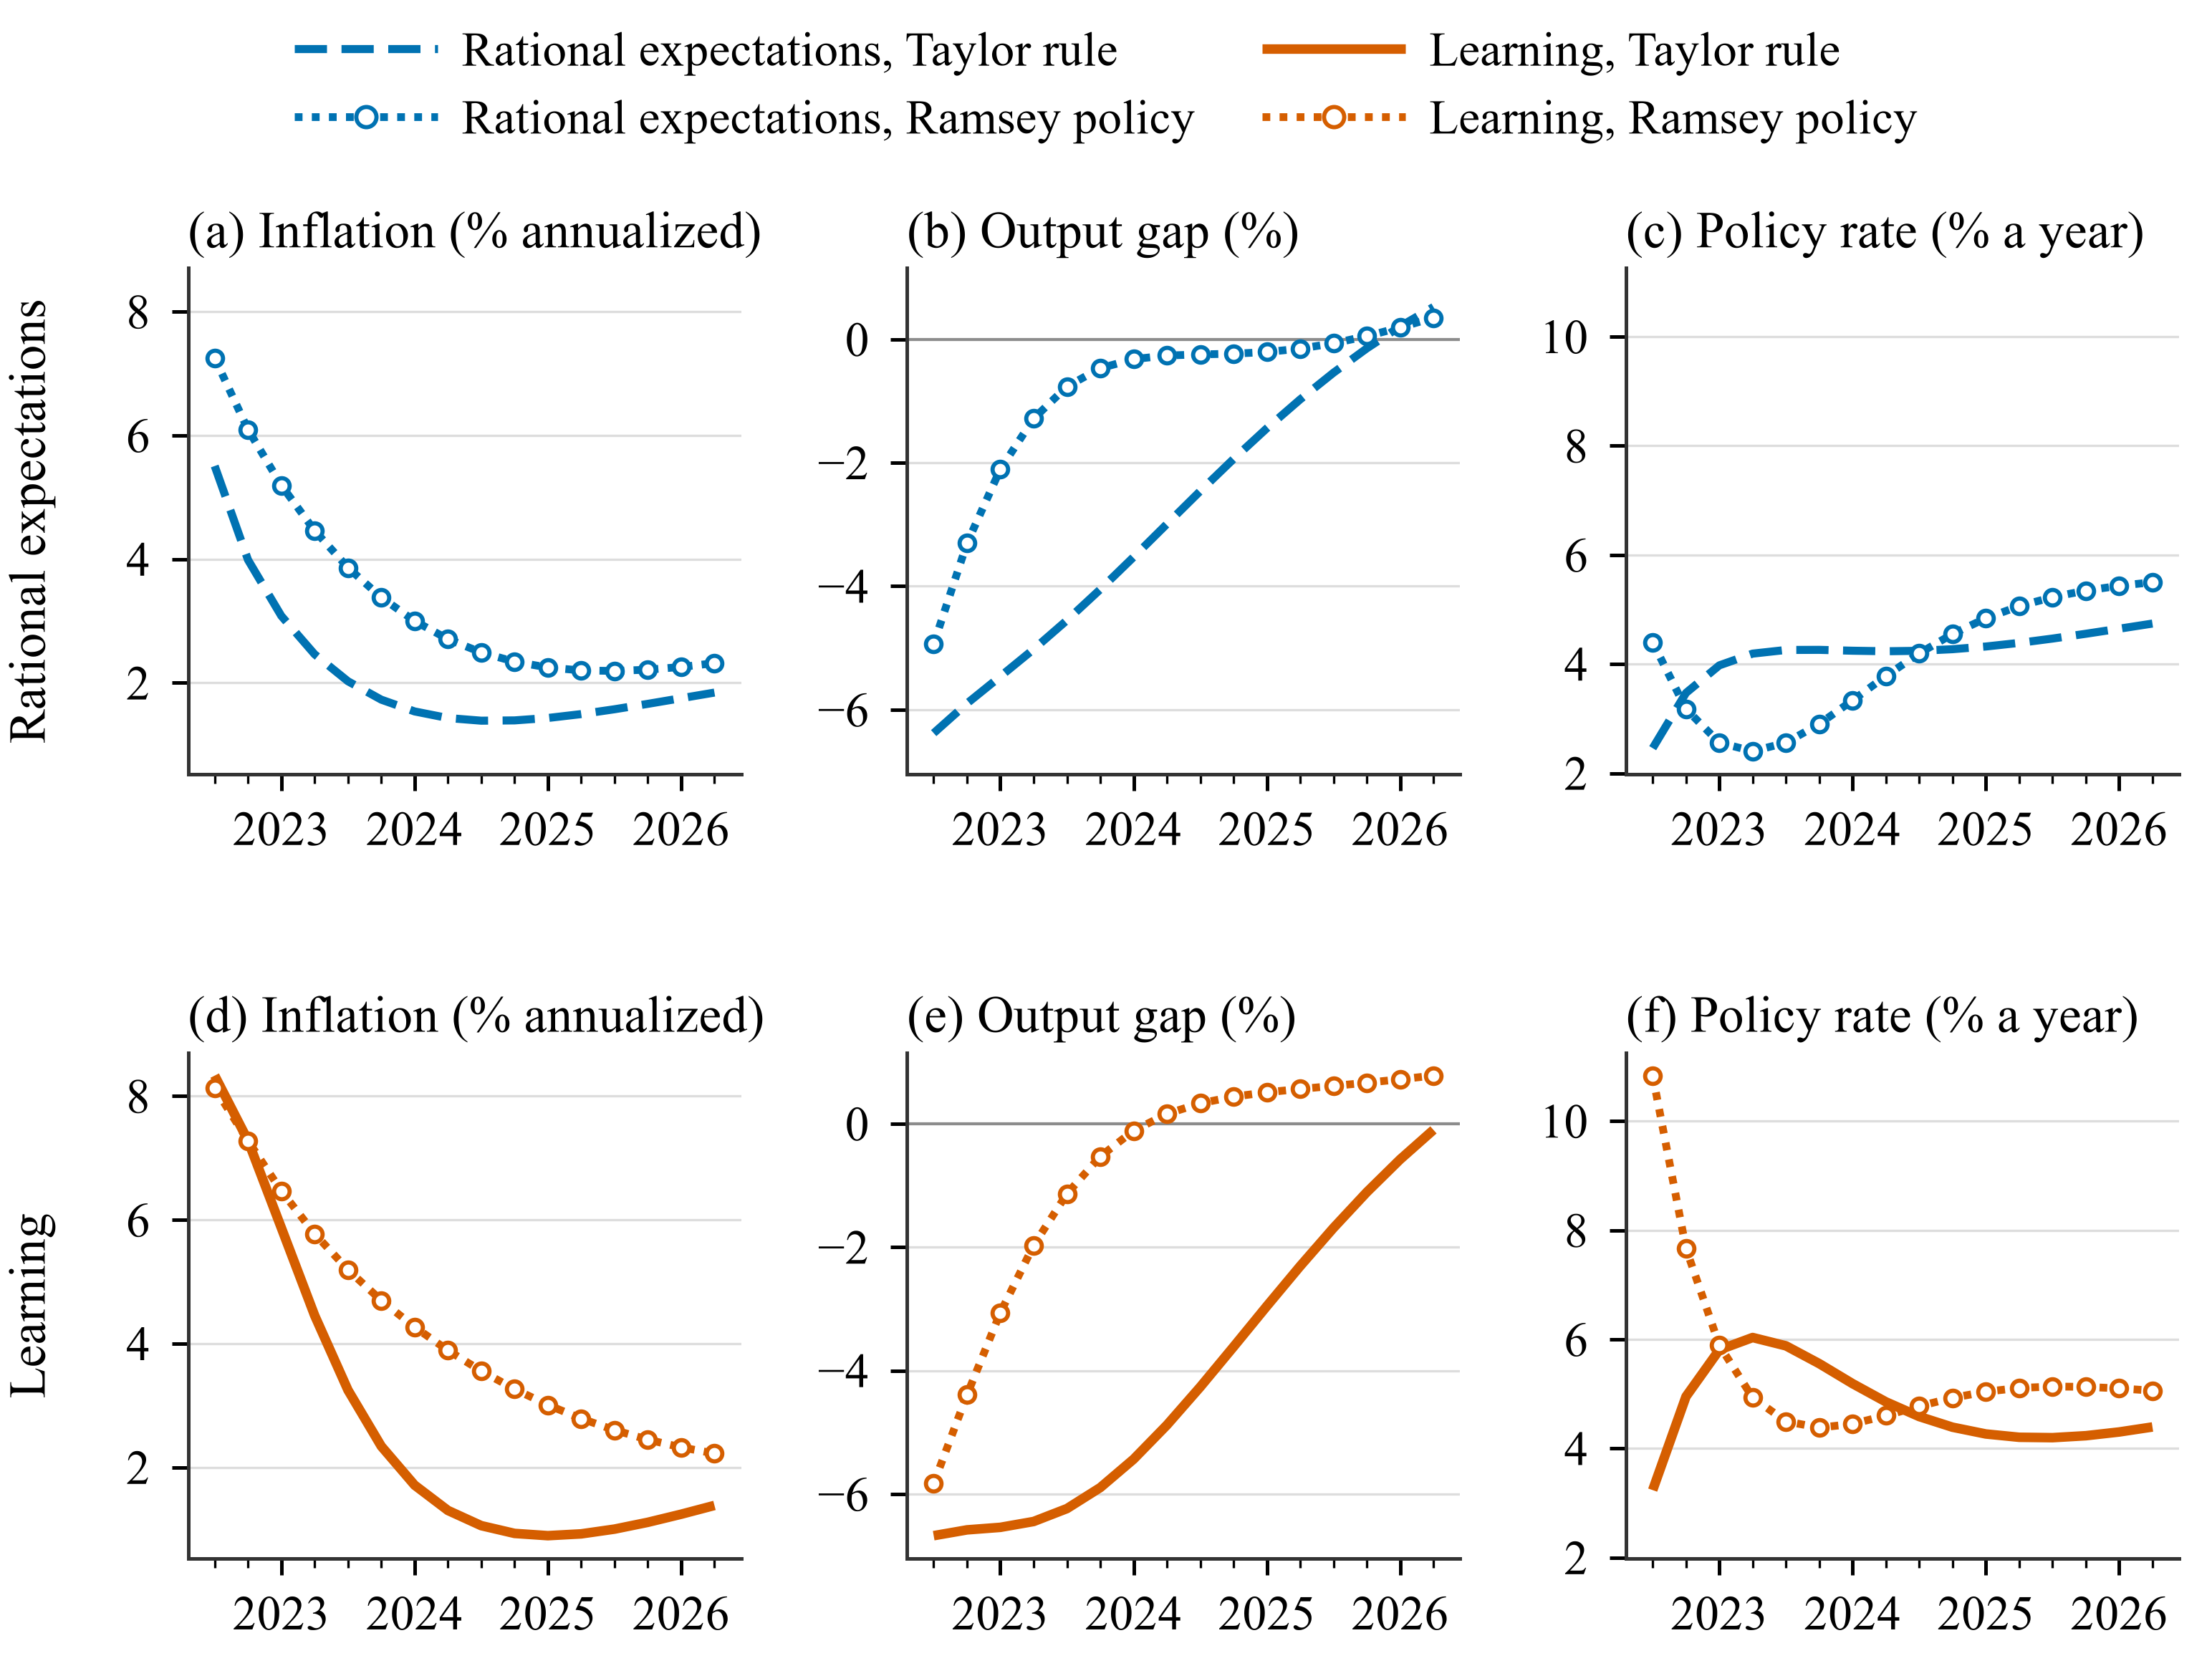
Ramsey policy under commitment (dotted) against the Taylor rule, balanced weights, zero
shocks. Inflation, output gap and policy rate; top row RE (a4_ramsey_balanced_re_mc), bottom
row learning (a4_ramsey_balanced_learn).
Discounted loss over 80 quarters:
| Weights | RE rule | RE Ramsey | Ratio | Learning rule | Learning Ramsey | Ratio |
|---|---|---|---|---|---|---|
| balanced | 230.1 | 127.7 | 0.56 | 359.4 | 184.5 | 0.51 |
| hawk | 104.9 | 51.5 | 0.49 | 175.4 | 94.6 | 0.54 |
| dove | 386.6 | 196.2 | 0.51 | 589.4 | 234.2 | 0.40 |
| smooth | 232.2 | 129.6 | 0.56 | 364.6 | 201.0 | 0.55 |
Balanced weights, averages 2022Q3-2026Q2:
| RE rule | RE Ramsey | Learning rule | Learning Ramsey | |
|---|---|---|---|---|
| Inflation (%) | 2.14 | 3.39 | 2.69 | 4.24 |
| Output gap (%) | −2.79 | −0.86 | −4.08 | −0.77 |
| Policy rate (%) | 4.17 | 4.08 | 4.75 | 5.47 |
- Ramsey policy roughly halves the loss under both expectation regimes.
- It trades a slower fall in inflation for a much smaller output gap.
- With learners the planner raises the rate sharply at the start: 10.83% in 2022Q3 against 3.24% under the rule (RE: 4.40% against 2.46%).
- Under learning the planner treats the current beliefs and shares as permanent and re-optimizes every quarter, honoring past commitments.
Each run also writes results/<id>/loss.csv with the contribution of each target.
Variations
% Another weight set
cfg = a4_ramsey_balanced_learn(); cfg.id = 'a4_ramsey_strict_learn';
cfg.policy.loss = struct('pinf', 1, 'ygap', 0.25, 'r', 0.1, 'dr', 0);
hetlearn.run(cfg);

% Another discount factor and the loss over the 16-quarter horizon only
cfg = a4_ramsey_balanced_re_mc(); cfg.id = 'a4_bal_mc_disc';
cfg.policy.discount = 0.99;
cfg.policy.loss_horizon = [];        % [] = forecast.horizon
hetlearn.run(cfg);
policy.loss is replaced as a whole: a target left out gets weight 0. All options:
Monetary policy.